Steps to Prepare for Digital Transformation
This is the second article in Q-Lana's Digital Transformation and Business Strategy Series on how financial institutions combine customer-centricity, risk management, data, and partnerships into a modern strategy. It covers groundwork needed before an institution attempts transformation.
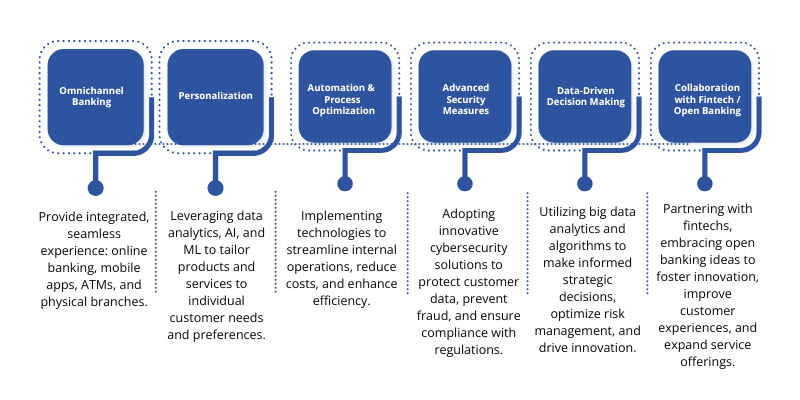
Digital transformation in financial services is most visible in six areas: omnichannel banking, personalization, automation, advanced security, data-driven decision-making, and fintech collaboration. While fintechs once seemed poised to replace banks, recent global shifts have reinforced the advantages of traditional financial institutions: stable funding, regulatory credibility, and established customer relationships.
Digital transformation is more than adopting new technologies. It is a profound shift in how an organization operates and delivers value to its customers. For financial institutions, it means leveraging digital tools and innovative strategies to increase efficiency, enhance customer experience, and remain competitive in a fast-changing market.
Six Key Areas of Digital Transformation
Today, digital transformation in financial services is most visible in six areas:
i. Omnichannel Banking
Customers expect seamless access across multiple channels, such as online banking, mobile apps, ATMs, agents, and physical branches. A consistent experience builds trust and convenience.
ii. Personalization
Using data analytics, AI, and machine learning, financial institutions can tailor products and services to customer needs. This shifts the model from "selling products" to providing solutions.
iii. Automation and Process Optimization
Technologies such as workflow automation and low-code platforms streamline internal operations, reduce costs, and improve flexibility as the business evolves.
iv. Advanced Security Measures
A modern digital infrastructure allows adoption of cutting-edge cybersecurity to protect data, prevent fraud, and remain compliant. Fraud is becoming more complex, especially as AI manipulates human interactions and exploits social media.
v. Data-Driven Decision-Making
Big data analytics and advanced algorithms enable informed decisions, stronger risk management, and innovation. This requires a clear data analytics strategy, a topic explored in later chapters of the series.
vi. Collaboration with Fintech and Open Banking
Partnering with fintechs and embracing open banking fosters innovation and expands services. This is perhaps the most revolutionary shift, but always subject to local rules and regulations.
Taken together, these six areas show that customers now expect nothing short of a revolution from their financial service providers. As Bill Gates once said: "Banking is necessary, banks are not."
The Fintech Challenge and the Traditional Bank Advantage
Fintechs initially seemed to have the upper hand. They leveraged modern technology, light regulation, agile operations, and flat hierarchies. In contrast, traditional financial institutions were often seen as bureaucratic, outdated, and overregulated.
But recent global events reshuffled the cards:
- The pandemic and geopolitical tensions disrupted markets
- Inflation and rising interest rates ended the era of cheap funding
- Trust and resilience became more valuable than speed alone.
Traditional institutions had advantages:
- Access to cheaper, more stable funding
- Strong credibility as licensed and regulated entities
- Large customer bases and rich data
- Experience and established risk management systems.
In short, traditional banks were back in the game. Yet, they cannot afford complacency. To seize this opportunity, they must accelerate their digital transformation.
Seven Steps to Prepare for Digital Transformation
How can financial institutions get started? We have identified seven essential steps:
i. Establish Objectives
Define the goals of transformation. Is it to improve legacy systems, attract new customers, or grow specific portfolios? Remember: digital transformation must be rooted in a broader business strategy. Transformation alone cannot be the strategy.
ii. Benchmark Against Competitors and Best Practices
Assess how your products, online presence, and digital services compare to peers, both traditional and non-traditional players.
iii. Evaluate Technology and Processes
Review your current systems, tools, and planning processes. Identify what is underutilized, what can be improved, and what new capabilities are required.
iv. Assess Culture
Transformation challenges the status quo and requires cultural alignment. Leaders must foster openness, provide structure, and secure support from digital experts, whether internal or external.
v. Define Customer Needs
Use data aggregation and segmentation to understand your audience. Align digital services with customer value drivers and product strategies.
vi. Prioritize Resources
Focus on a few projects first to create quick wins. Transformation is a journey. Start small, then scale.
vii. Promote Buy-In
Secure enthusiastic support from staff and customers through clear communication, training, and change management programs. Internal and external marketing are essential to sustain momentum.
What's Next in the Series
Digital transformation requires thorough planning and strong leadership, but above all, it must be anchored in a clear business strategy. Without strategic alignment, technology investments will deliver little impact.
In the next chapter, we will look at how to assess an institution's readiness for digital transformation. Later in the series, we will dive deeper into the strategic business planning needed to build a digitally focused financial institution.
About This Series
This article is part of Q-Lana's Digital Transformation and Business Strategy series, exploring how financial institutions combine customer-centricity, structured risk management, data analytics, and strategic partnerships into a modern business model.
The complete series includes:
- Digital Transformation With Q-Lana
- Are You Ready for Digital Transformation?
- Let's Develop a Business Strategy
- Customer Centricity
- Risk Management
- Data Analytics
- Risk Appetite and Relationship Pricing: Part 1
- Risk Appetite and Relationship Pricing: Part 2
- The Q-Lana Platform
- Risk Sharing Concept, and this article.
Continue the Conversation
Talk to the team. Senior-to-senior. No sales call.
Subscribe to Q-Lana Weekly. One newsletter, five lenses, free, no paywall.