The Minimum Viable Data Architecture for SME Lending
This is the third article in Q-Lana’s four-part Data Management Series, exploring minimum viable data architecture and how it helps SME lenders organize fragmented data for better credit decisions.
Most SME lending data initiatives fail for a predictable reason. They try to build the perfect architecture before delivering any value: enterprise data lakes, complex integration layers, multi-year IT roadmaps, and dozens of dashboards, but only a few of them are trusted.
After months (or years), the business still asks the same question: Can we make faster, better credit decisions?
Too often, the honest answer is no. The problem is not ambition. The problem is sequence.
In SME lending, data architecture must enable decisions now, not promise insight later. That is why the most effective institutions don't start with a "target architecture." They start with a minimum viable data architecture, designed to work with what already exists, prove value quickly, and scale with discipline.
Why Big Data Architectures Fail in SME Lending
Large-scale data programs often fail not because they are technically flawed, but because they misunderstand how SME lending actually works.
Typical failure patterns include:
- Perfection paralysis: Projects stall while teams debate future use cases instead of fixing today's problems
- Over-engineering: Sophisticated architectures are built before data quality, ownership, or definitions are resolved
- Low adoption: Business users don't trust the outputs and revert to spreadsheets and emails
- Delayed credibility: By the time results appear, priorities and people have changed
SME lending is not a laboratory environment. It is fast, judgment-driven, and operationally intense. A data architecture that does not deliver early, visible value will lose support, regardless of how elegant it looks on paper.
What is Minimum Viable?
"Minimum viable" does not mean simplistic or temporary.
It means:
- Lean rather than bloated
- Connected rather than fragmented
- Controlled rather than ad hoc
A minimum viable data architecture (MVDA) focuses on enabling the next best decision, not the perfect future state. Its purpose is to answer four practical questions, reliably and repeatedly:
- Do we have all relevant information for this decision?
- Is it consistent and trusted?
- Can we trace how the decision was made?
- Can we reuse this information next time?
If an architecture supports these questions, it is doing its job.
The Six Building Blocks of a Minimum Viable Data Architecture
Across institutions and markets, six architectural components consistently form the backbone of an effective SME lending data setup. They are modular, technology-agnostic, and designed to evolve.
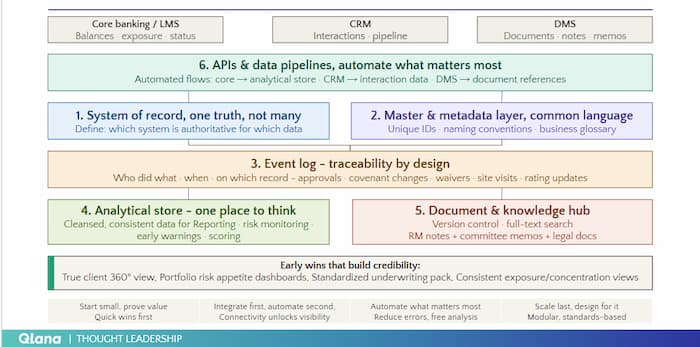
1. System of Record: One Truth, Not Many
Every institution already has systems that matter:
- Core banking or loan management
- CRM
- Accounting systems
The problem is not their existence, it is ambiguity. A minimum viable architecture clearly defines which system is authoritative for which data:
- Customer identity
- Facility balances
- Repayment status
- Exposure amounts
Without this clarity, reconciliation becomes a permanent activity, and trust erodes.
You do not need fewer systems. You need clear authority.
2. Master & Metadata Layer: Common Language, Shared Meaning
Data without definition is noise. This layer establishes:
- Unique identifiers for customers, facilities, and collateral
- Standard naming conventions
- A business glossary that defines fields and metrics
This is not academic documentation. It is what allows different teams, such as credit, risk, finance, and audit, to speak the same language.
Institutions often underestimate this step. In reality, it is one of the highest-return investments in data work.
3. Event Log: Traceability by Design
Every meaningful action in SME lending matters:
- Credit approvals
- Covenant changes
- Waivers
- Site visits
- Rating updates
A structured event log records who did what, when it happened, and on which data object. This creates decision lineage, the ability to reconstruct not just outcomes, but reasoning.
Event logs are the foundation of audit readiness, model validation, explainable AI, and institutional learning. Without them, institutions rely on memory and email trails. That does not scale.
4. Analytical Store: One Place to Think
This is where trusted, cleansed data comes together for reporting, portfolio analysis, risk monitoring, and early warning systems. Whether implemented as a warehouse or lakehouse is secondary. What matters is that data is consistent, refreshed predictably, and separated from operational noise.
This store is not for experimentation alone. It is for decision support.
5. Document & Knowledge Hub: Where Context Lives
SME lending is document-heavy:
- Financial statements
- Credit memos
- RM notes
- Committee minutes
- Legal documentation
A minimum viable architecture consolidates these into a single document and knowledge hub with strict version control, searchable content, and links to structured data. This is where qualitative insight meets quantitative facts. Institutions that neglect this layer lose the "why" behind decisions, even if they retain the "what."
6. APIs & Data Pipelines: Automate What Matters
Manual file transfers are a hidden tax on SME lending.
Automated pipelines reduce errors, improve timeliness, and free up analytical capacity.
A minimum viable setup focuses on high-impact flows first:
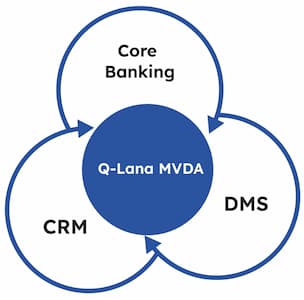
- Core systems → analytical store
- CRM → interaction data
- DMS → document references
Automation follows clarity, not the other way around.
Early Wins That Build Credibility
The purpose of a minimum viable architecture is to show value early. Typical early outputs include a true Client-360 view, portfolio risk appetite dashboards, standardized underwriting packs, and consistent exposure and concentration views.
These do not require perfection. They require consistency. Once users see reliable outputs, trust builds, and adoption follows.
Architecture Does Not Replace Governance
A common misconception is that architecture enforces discipline. It does not.
Architecture enables discipline. Governance enforces it. Without clear ownership, data quality rules, and follow-up mechanisms, even the best architecture will decay over time. This is why architecture and governance must evolve together, a topic we will address explicitly in the next article.
Why This Approach Works for SME Lending
The minimum viable approach succeeds because it aligns with reality:
- SME portfolios grow incrementally
- Credit judgment evolves over time
- Resources are finite
- Trust must be earned, not declared
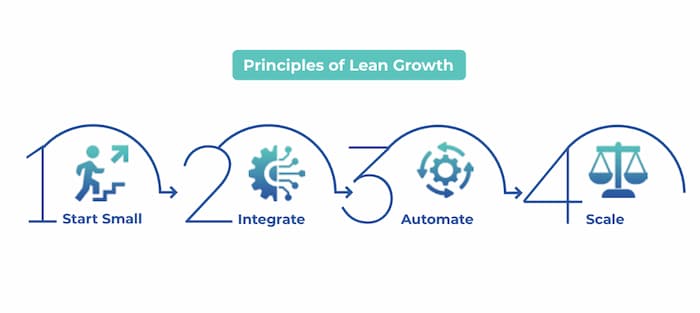
Institutions that adopt this approach move faster not because they do less, but because they do the right things first.
At Q-Lana, this philosophy is embedded in how we design platforms and implementation journeys. We focus on early decision impact, pragmatic sequencing, and architectures that serve the business, not the other way around.
About This Series
This article is part of Q-Lana's four-part Data Management series on how modern SME lenders turn fragmented information into decision intelligence.
The complete framework includes the articles on:
- Concepts of good data management
- The eight critical data domains
- Data governance, quality, and knowledge management, and this article.
The full content in a more detailed version is available in Q-Lana's Data & Knowledge Management Whitepaper.
Continue the Conversation
Talk to the team. Senior-to-senior. No sales call.
Subscribe to Q-Lana Weekly. One newsletter, five lenses, free, no paywall.
Read the related white paper. Frameworks built to be deployed.