RAROC in Practice: How to Separate Profitable Lending from Safe-But-Costly Deals
This is the fourth article in our 5-part Credit Risk Management series. We explore RAROC as a key measure of whether lending decisions create value, helping lenders distinguish between safe lending and genuinely profitable, sustainable strategies.
By the time most institutions talk about profitability, the most important decisions have already been made. The loan is booked. The structure is fixed. The capital is committed. What follows (margin monitoring, performance reviews, explanations to the Board) is largely a rearview mirror exercise.
True steering happens earlier. It happens at the intersection of risk, capital, and return. And it requires a metric that most institutions either misuse, underuse, or ignore entirely. That metric is Risk-Adjusted Return on Capital (RAROC).
Why Margins Lie
Most lending decisions are still driven by margin thinking: is the rate attractive, does it beat the hurdle rate, does it grow the book?
Margins are intuitive but omit the variable that matters most in a leveraged institution: how much capital is consumed to earn that return. Two loans with identical margins can have radically different impacts. One may consume little capital and be genuinely value-creating. The other may tie up significant equity and quietly destroy shareholder value, all while appearing equally profitable on the income statement.
This is the structural blind spot that margin-driven growth strategies share. They optimize income while ignoring volatility and capital scarcity. Eventually, the cost appears, in stress tests, in capital raising, in conversations with regulators.
As Q-Lana puts it:
A loan is not good because it has a high interest rate. It is good if it delivers an adequate return per unit of capital consumed.
Want to go beyond the theory?
Learn how RAROC, credit risk, and risk appetite can support better lending and capital allocation decisions.
What RAROC Actually Measures
At its core, RAROC answers one question: are we being paid enough for the capital we put at risk?
The logic flows directly from the framework established in Articles 1 to 3:
- Expected Loss reflects the cost of risk, provisioned and priced in
- Unexpected Loss defines how much equity capital must be held against the exposure
- Capital is the scarce resource that shareholders expect to be compensated for
- RAROC expresses return relative to that capital, not relative to loan size or headline margin
This reframes profitability entirely. A loan with a high interest rate and poor collateral may generate less value than a well-secured loan at a lower rate, because the capital it demands is far greater.
RAROC makes that trade-off explicit, visible, and comparable across every transaction in the portfolio.
The Q-Lana White Paper on Credit Risk includes a full worked RAROC calculation, including sensitivity analysis across loan size, collateral quality, and cross-selling scenarios, for teams that want to see the full mechanics before embedding this into their own pricing processes
From Risk Models to Business Decisions
RAROC is where the analytical chain from Articles 1 to 3 stops being abstract and becomes operational.
Unexpected Loss defines capital consumption. Capital consumption defines the denominator of RAROC. The numerator, risk-adjusted revenue, reflects pricing, fees, funding costs, and operating expenses.
When RAROC is visible at the transaction level, it changes the nature of credit discussions:
- Weak structures are exposed, their capital cost is no longer invisible
- Long maturities reveal their true price, they inflate Unexpected Loss non-linearly
- Collateral quality becomes economically meaningful, not just a security comfort Pricing decisions become factual rather than negotiated by feel
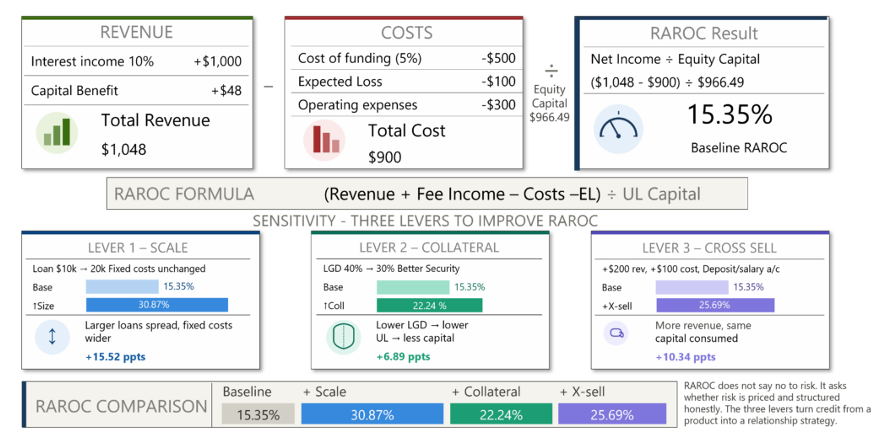
- RAROC does not say no to risk. It asks whether risk is priced and structured honestly.
▌ The executive question
In your institution, does the credit committee review RAROC before approval, or review it afterwards to explain performance?
Putting It Into Practice
The Four Real Levers of RAROC
RAROC rarely improves by simply raising interest rates. It improves because decisions get smarter. In practice, four levers matter most.
1. Structure and Maturity
Long maturities increase exposure to uncertainty and inflate capital requirements. Shortening tenor often improves RAROC more than repricing, without increasing nominal cost to the borrower.
2. Collateral Quality
Better collateral reduces LGD, lowers Unexpected Loss, and directly frees capital, creating room for competitive pricing without sacrificing risk-adjusted profitability: one of the few win-win levers in credit structuring.
3. Scale and Operating
Efficiency Operating costs are largely fixed. Larger, well-structured exposures often deliver higher RAROC than small, operationally intensive loans, despite appearing riskier on the surface. This dynamic is frequently overlooked in portfolio strategy
4. Relationship Economics
Cross-selling deposits, transaction accounts, or fee-based services improves total return without increasing capital consumption. RAROC captures this reality explicitly, and it is one of the strongest arguments for relationship banking over transactional lending. This connects directly to the ideas in our Customer Centricity: deep client relationships are not just a service philosophy. They are a capital efficiency strategy.
These four levers turn credit from a product into a relationship strategy.
RAROC as a Management Tool, Not a Risk Metric
Here is where most institutions miss the point. RAROC is frequently used as a post-approval reporting metric, a number calculated after the decision to explain what happened. That misses its real power entirely.
Used correctly, RAROC:
- Informs approval decisions before capital is committed
- Shapes product design, which structures generate value and which destroy it
- Guides portfolio rebalancing toward higher-returning segments
- Links frontline decisions to Board-level objectives
- Aligns incentives across relationship management, credit, and finance
When RAROC is embedded in the approval process, relationship managers understand why certain deals are declined. Credit committees focus on structure, not just risk ratings. Management can see, segment by segment, where the institution is actually creating value after capital, and where it is not.
RAROC becomes a common language between business, risk, and finance. That alignment is rare, and it is powerful.
RAROC and Risk Appetite: Two Sides of the Same Coin
RAROC cannot exist in isolation. It operates within the institution's risk appetite. A high RAROC target implies higher pricing, tighter structuring, or lower volume; a lower threshold implies strategic growth priorities, higher capital buffers, or greater tolerance for volatility. Neither is inherently right or wrong. What's dangerous is misalignment: aggressive volume growth paired with conservative capital, or high RAROC targets alongside weak pricing power. RAROC forces coherence between ambition and resilience.
Why RAROC-Driven Institutions Lend Through the Cycle
In downturns, most institutions retreat: not because opportunities disappear, but because capital becomes scarce and management lacks the analytical confidence to distinguish good risk from bad risk. Institutions that understand RAROC know which segments still deliver acceptable risk-adjusted returns and which structures protect the downside without killing the upside. As competitors pull back indiscriminately, these institutions lend selectively and often strengthen their market position. RAROC does not make institutions conservative: it makes them confident under pressure.
▌ Q-Lana’s approach
RAROC is one of the areas where Q-Lana’s competency in credit risk management is most tangible. It is integrated directly into our lending platform’s pricing logic and portfolio dashboards, so institutions can see, in real time, how each decision affects capital consumption, risk-adjusted return, and portfolio resilience. The goal is not to maximize a ratio. It is to allocate scarce capital where it creates sustainable value. For teams building or refining their RAROC frameworks, our Financial Skills Campus class on Risk Appetite and RAROC provides both the conceptual grounding and practical tools to get started.
▌ Q-Lana Knowledge Resources
White Paper: Credit Risk and Risk Appetite, full RAROC worked example and sensitivity analysis in Part 1, Section 5. Download at q lana.com.
Q-Lana Financial Skills Campus (FSC): Class 2, Risk Appetite and RAROC. Covers RAROC calculation, the four improvement levers, and embedding RAROC into credit decision workflows.
FSC Course: Risk-Based Pricing, connecting RAROC to loan structuring, product design, and relationship economics in everyday lending practice.
Coming Next
If RAROC tells us whether individual decisions create value, the final question becomes: how do we ensure thousands of daily decisions collectively move the institution in the right direction?
About this Series
This article is part of Q-Lana's Five-part Credit Risk Management series, exploring how institutions move from intuition to a disciplined, measurable approach to credit risk, capital, and pricing.
The complete series includes:
- Credit Risk Starts with Measurement, Not Instinct
- Provisions Are Not Enough: Understanding Unexpected Loss
- Capital Is a Signal, Not a Constraint
- Risk Appetite as the Operating System for Strategy, and this article.
Continue the Conversation
Talk to the team. Senior-to-senior. No sales call.
Subscribe to Q-Lana Weekly. One newsletter, five lenses, free, no paywall.
Read the related white paper. Frameworks built to be deployed.