Credit Risk Concepts: Introduction
Welcome to this series of the credit risk concepts where we explore key quantitative techniques that support pricing, capital planning, and performance measurement, simplifying core elements like PD, LGD, and EAD for practical use in lending institutions.
Credit risk the most critical risk category for any lending-focused financial institution. It underpins a wide range of financial activities, from traditional term loans and complex structured finance to trading products. A solid understanding of credit risk is essential for accurate pricing, effective portfolio management, and overall institutional resilience.
Over time, financial institutions have developed diverse methodologies to assess credit risk. These range from straightforward scorecards based on a handful of indicators to in-depth, multi-page assessments incorporating comprehensive financial modeling. While the analytical foundations of these approaches are addressed in other publications, this series focuses on Credit Risk Modeling—the quantitative framework that builds on credit analysis and supports pricing decisions, capital planning, and strategic steering. This Concept Note provides a structured, step-by-step exploration of the key components of credit risk modeling.
Quantifying credit risk is a cornerstone of effective risk management for financial institutions.
By breaking credit risk into measurable components, institutions gain the ability to assess, price, and manage their exposures with greater precision.
This chapter introduces the three foundational variables: Probability of Default (PD), Loss Given Default (LGD), and Exposure at Default (EAD).
Probability of Default (PD), Loss Given Default (LGD), and Exposure at Default (EAD).
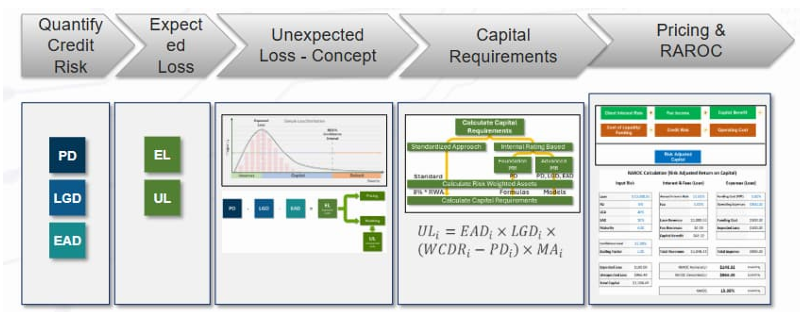
Chapter 1: Quantifying Credit Risk
This chapter of the credit risk concepts explains the three core variables:
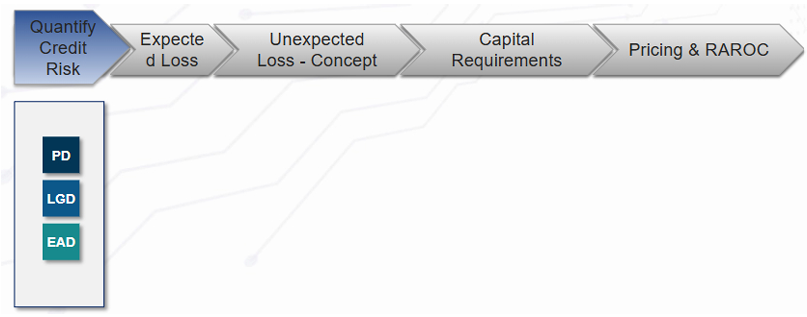
i. Probability of Default (PD)
ii. Loss Given Default (LGD)
iii. Exposure at Default (EAD)
These variables form the foundation for all credit risk measurement and modelling.
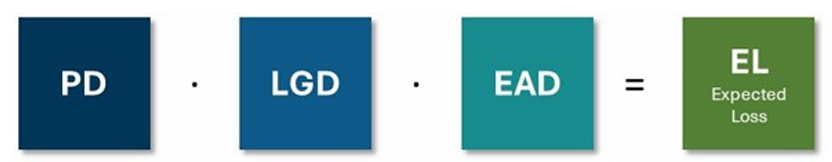
Chapter 2: Expected Loss
This chapter covers the definition, calculation, and application of Expected Loss (EL). We also emphasize the role of expected loss in provisioning, pricing, and portfolio monitoring.
Chapter 3: Unexpected Loss
In this chapter, we explore Unexpected Loss (UL) in terms of how it is modelled using simulations, its role in capital adequacy, and why it is critical for absorbing shocks beyond expected defaults.
Chapter 4: Capital Requirements
Capital requirements link credit risk modelling to regulatory frameworks (Basel I–IV). The chapter details how financial institutions can calculate capital needs at the individual loan level using standardized and internal models
Chapter 5: RAROC
In this final chapter of our credit risk series, we introduce you to Risk-Adjusted Return on Capital (RAROC).
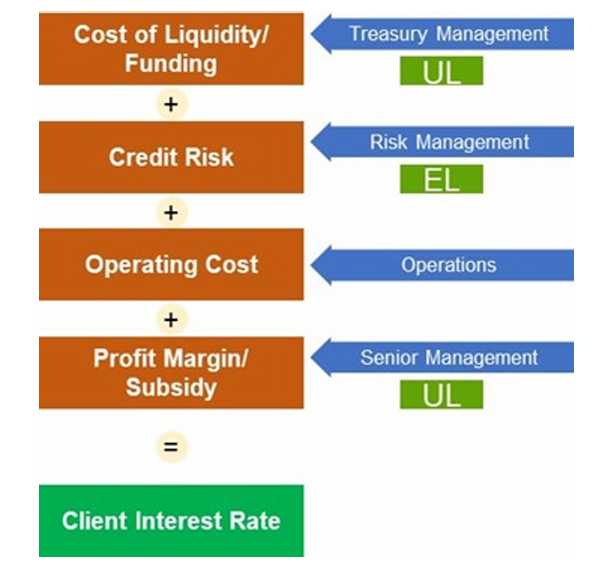
We explain how financial institutions can align profitability with capital efficiency, using risk-adjusted metrics for loan pricing and strategic steering.
About This Series
This article is part of Q-Lana's Credit Risk Concepts series, exploring the quantitative techniques that support pricing, capital planning, and performance measurement.
The complete series includes:
- Quantifying Credit Risk Using PD, LGD and EAD
- Expected Loss in Credit Risk: Formula, Calculation & Examples
- Unexpected Loss (UL): Capital Buffers, Calculation & Portfolio Implications
- Quantifying Capital Requirements for Individual Loans
- RAROC: How to Calculate Risk-Adjusted Return on Capital (With Worked Example)
- Credit Risk Series Summary, and this introduction.
Continue the Conversation
Talk to the team. Senior-to-senior. No sales call.
Subscribe to Q-Lana Weekly. One newsletter, five lenses, free, no paywall.
Read the related white paper. Frameworks built to be deployed.